De-risking a multi-brand Internet Banking MVP for 215K+ customers
How concept testing with 12 customers challenged an app-based feature list before build, and reshaped what shipped across three banks.
Lead UX Researcher
What changed?
- 3 statement features moved into the MVP
- 3 new features added that the app-based list had missed
- Personas rebuilt after only 1 of 12 matched
Scale
- Customers in scope at the start 215K+
- Banks on one codebase3
- Legacy platforms to decommission2
Status
- The MVP this research shaped launched with the ME migration, completed in 2026Source: BOQ FY26 results
3 banks, 2 legacy platforms, one codebase
The business wanted Internet Banking to copy the app. I tested what customers need from a laptop instead.
BOQ Group was moving Virgin Money, BOQ and ME Bank onto one cloud banking platform, app first: Virgin Money in 2021, myBOQ in 2022, then ME Go, a mobile-only app, in 2023. The goal was scale and a lower cost to serve. Internet Banking came last: an MVP to replace two legacy platforms, starting with ME Bank.
The Day 1 feature list was drafted from what the app already did. My brief was to test it with customers and confirm what the MVP should contain.
All three banks shared one codebase, so a wrong call at ME Bank would carry through to Virgin Money and BOQ.
Existing Internet Banking customers hadn’t chosen to move. If a task they relied on was missing or hard to find, they’d be locked out, call the contact centre, or leave.
- Ownership
- Led concept testing & persona rebuild · Co-designed the Internet Banking roadmap
- Stakeholders
- Heads of Design & Product · Service Design Lead · PM · BA · Eng lead · Compliance
- Timeline
- ~2 months · Discovery → MVP handover
- Methods
- Service blueprint · Concept testing · Persona rebuild · Prototyping
Questioning the mobile-first mandate
The MVP rested on two beliefs, and neither had been tested with customers.
The Day 1 feature list was taken from what the app already did, on the assumption that Internet Banking should mirror it.
Customer analytics also suggested older customers prefer Internet Banking, which had become a proto-persona nobody had validated.
A list built from the app tells you what exists, not what a customer expects when they sit down at a laptop. That raised four questions, and I built the research around them:
- What do customers need from desktop that mobile doesn’t give them?
- Where does parity matter, and where should each channel lead with its strengths?
- Do the personas hold up?
- Which features earn a place on Day 1?
Task, not age, drove platform choice
12 customers, 10 banking scenarios: desktop won for detail, mobile for speed.
The business asked me to validate a feature list. What it needed to know was how customers actually bank.


I didn’t just show people the feature list and ask if it looked right. I asked open questions first and let them answer in their own words, then gave them the real list to rank. The two answers didn’t match. Asked what they’d want under Profile, people named personal details, payment limits and password. Given the full list, they put Manage cards and Statements & docs in their top three. Those features mattered to them, but they didn’t think of them as Profile features, so the placement wasn’t intuitive. A yes or no on the list would have missed it. The business asked me to validate a feature list, and asking this way showed what the list got wrong, not just whether people liked it.


Most participants preferred mobile overall. But the task, not the person, decided the channel.
- Internet Banking for reading detail or filling in fields: opening an account, large transfers, transaction search, statements, home loans and updating details.
- Mobile for quick actions: payments, alerts and balance checks.
- Habit played a part too: 7 of 12 researched a product on the bank's website and carried on to sign up in Internet Banking.

The only reason I’m still [accessing] online is because of [the] difference in features and the visual appearance … If the apps had more features, I’d probably rarely go into internet banking.
A list built from the app could only include what the app already did. Customers rated four features as high-impact that the app didn’t have:
- Live chat for help: 7 of 12 preferred it to calling, for faster answers and a saved history. The 3 who’d rather call were all over 50 and wanted a person for bigger problems.
- Password-less login with a mobile number and app verification: most were open to it, but some hesitated over security.
- Customisable dashboard: customers expected accounts and balance first, and 7 liked choosing what else shows.
- Home loan calculator to understand repayments.


Retiring the age‑based persona
Age didn’t predict the channel. The task did.
Only 1 of 12 participants matched the age-based proto-persona: a Virgin Money customer aged 65.
Age was the wrong lens. People switched channels depending on what they were doing, so their age couldn’t predict where they’d bank.
I rebuilt the personas around how people think in the moment, not who they are:
- Internet Banking mode: detail and bigger decisions, like home loans, large transfers and statements. Room to read, compare and check.
- Mobile mode: quick and on the go, like payments, alerts and tracking spending. Convenience first.
The personas fed the Foundation blueprint and feature prioritisation across all three brands. Designing for the task, not the age group, meant each channel could do what it’s best at.
Age-led personas → behaviour-led personas
Drag to compare

Turning findings into a build brief
Not a copy of the app. Parity where it mattered, more depth where the task needed it.
With the Service Design team, I turned the findings into CX principles the squad could test every MVP decision against:
- Task-led, not channel-led: put each feature where customers naturally reach for it.
- Consistent core: same layout, language and key features across app and Internet Banking.
- More depth on desktop: use the bigger screen for detail, search and documents.
- Inclusive by default: clear steps and context for customers with cognitive accessibility needs.
I handed the principles, rebuilt personas and prioritised feature list to the web team. A senior designer took the interface from there.
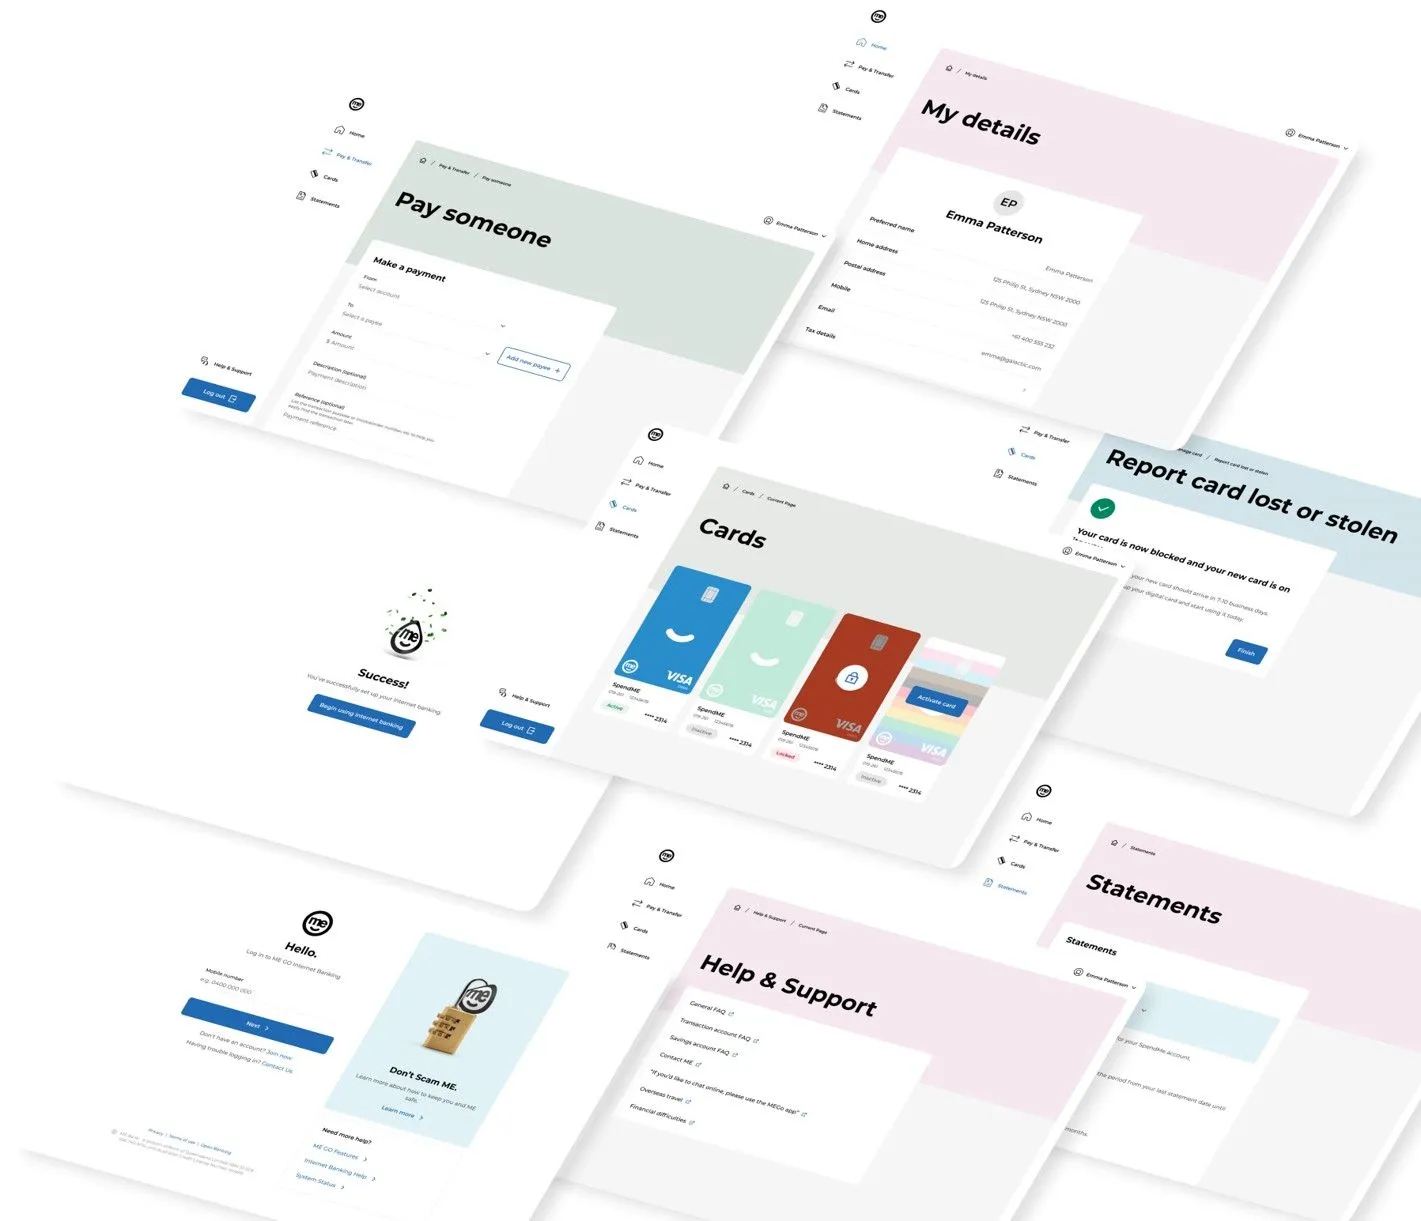
Changing what shipped on Day 1
The research reshaped the MVP. The ME migration completed by August 2026.
At a feature assessment, the IB working group acted on the findings. Several of the features were flagged as likely to reduce contact centre calls, but the research could only predict that, not measure it.

AI did the groundwork, not the thinking:
- Where it helped: first drafts of the screener and moderation guide from my brief, quick counts on scaled questions (1–10 ratings), and first-pass clustering of 402 tagged highlights.
- How I checked it: I added what was missing and corrected what was not accurate or true. Every cluster went back to the session clip it came from: if a theme couldn't be traced to what a participant said or did, it didn't make the playback.
- What stayed mine: the research plan, the moderated sessions, every answer that wasn't a simple yes/no or a number, the synthesis themes, the persona rebuild and the MVP recommendations.
I also redesigned the playback format so findings were easier to act on, and built Dovetail templates and a shared tagging system the team could reuse. Compared with my earlier studies of similar size, planning-to-synthesis time dropped from about two weeks to about one, and insights became easier to find across teams.
The bigger lesson was earning the room. When stakeholders don’t yet value research, the case shifts from “we should validate” to “here’s what we risk if we don’t”.


Customers chose chat over calls for support. We couldn’t yet measure the impact.
With the contact centre already stretched, live chat looked like an easy win, and 7 of 12 preferred it. But seen as one system, chat could simply shift the load rather than reduce it. The research confirmed the preference, not the saving. Next time I’d bring in contact centre data early, so the decision rests on evidence, not just appeal.